Legal Due Diligence in Kuwait | Lawyer Khaled Mufrej Al-Dalmani
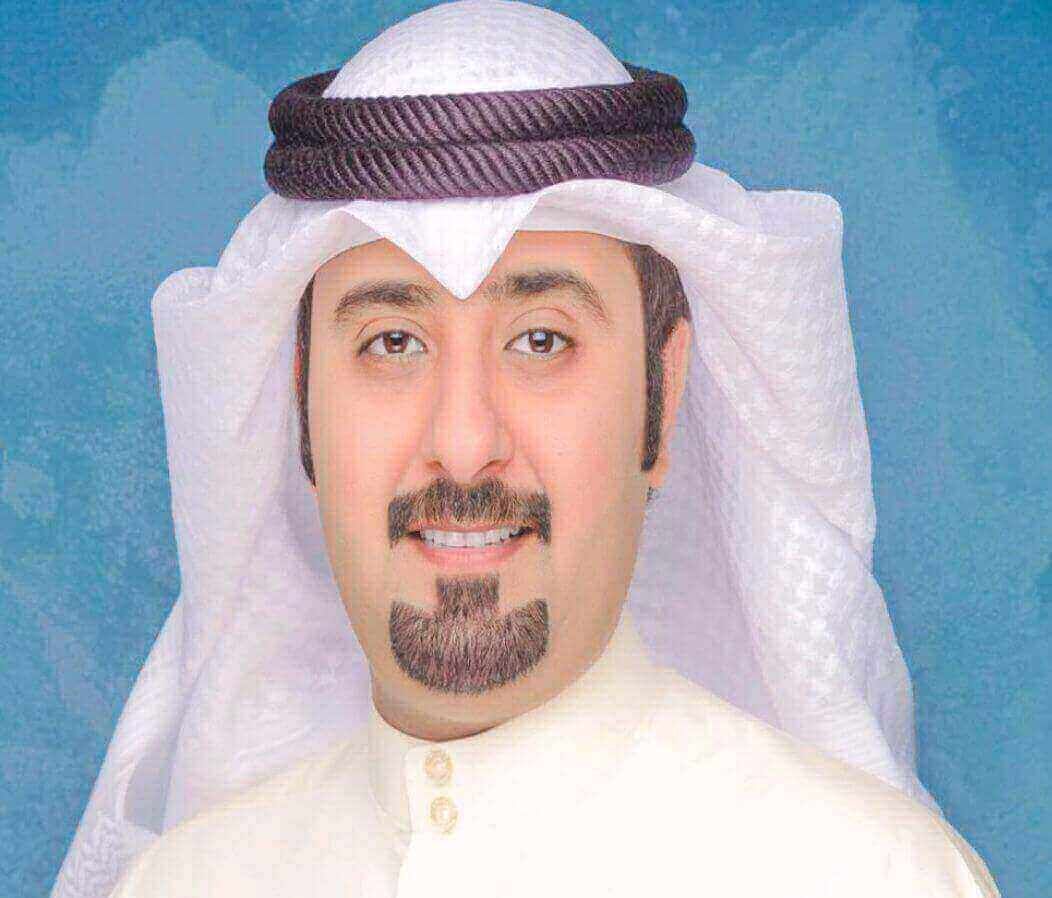
Legal due diligence in Kuwait is a decision-focused review of documents, rights, liabilities and transaction risks before an acquisition, investment, financing, restructuring or major commercial commitment. Lawyer Khaled Mufrej Al-Dalmani assists buyers, investors, lenders, boards, founders and overseas transaction teams that need a structured assessment of a Kuwait business or contract portfolio.The purpose is not to promise that every risk can be found. It is to define the scope, test the available evidence, identify material issues, record limitations and convert findings into practical actions before signing or closing. For general legal support in Kuwait, see English-speaking legal services in Kuwait.
When legal due diligence is needed
- Acquiring shares, assets, a business line or a material contract portfolio.
- Making a direct investment, joint venture or strategic partnership in Kuwait.
- Providing finance, security or a commercial guarantee.
- Restructuring ownership, operations or group companies.
- Entering a long-term distribution, supply, technology or outsourcing relationship.
- Preparing a company for investment, sale or a governance review.
The review can be buyer-side, investor-side, lender-side or a vendor readiness exercise. Each requires a different scope, materiality threshold and reporting format.
What the review can cover
A full legal due diligence exercise may include corporate records, licences, ownership and authority, material contracts, disputes, employment matters, assets, intellectual property, financing, security, insurance, data and regulatory issues. A contract-focused review is narrower and examines agreements that are material to revenue, operations, cost, control or closing.The scope should state the target entity or assets, transaction structure, review period, document categories, financial or operational thresholds, applicable jurisdictions, excluded matters and deadline. Specialist tax, accounting, technical or regulatory advice may be required in parallel and should not be assumed to fall within a general legal review.
Due diligence is not contract drafting
Due diligence investigates existing rights and obligations across a transaction or portfolio. Drafting creates or negotiates terms for a particular future relationship. A diligence report may recommend a consent, disclosure, condition precedent, warranty, indemnity, price mechanism or post-closing action, but it does not silently rewrite the underlying agreements. For a new or amended agreement, see international commercial contract drafting in Kuwait.
Transaction risk matrix
| Finding | Possible transaction impact | Typical response to consider |
|---|---|---|
| Change-of-control restriction | The transaction may require consent or permit termination. | Confirm the trigger, timing and whether consent should be a closing condition. |
| Assignment prohibition | Rights or obligations may not transfer with the proposed structure. | Review the transfer mechanics and alternative structures before commitment. |
| Automatic renewal or exclusivity | The target may remain bound to price, volume, territory or duration commitments. | Record notice dates and assess amendment or exit options. |
| Broad indemnity or uncapped liability | Historic or future exposure may exceed the expected deal value. | Quantify available facts and consider warranties, indemnities or price protection. |
| Missing signature, annex or amendment | The operative terms and enforceability may be uncertain. | Request complete executed records and state the limitation if unavailable. |
| Licence or corporate-record inconsistency | The target's activity, authority or ownership evidence may not match the deal assumptions. | Verify against current official records and obtain corrective documents where needed. |
Documents required for a reliable review
- Transaction structure, term sheet, timetable and current draft transaction documents.
- Constitutional records, shareholder information, authorisations and signing authorities.
- Current commercial licences, registrations, permits and relevant regulator correspondence.
- A complete contract register with signed contracts, schedules, amendments, side letters and notices.
- Customer, supplier, lease, financing, guarantee, agency, distribution and insurance documents.
- Details of disputes, claims, investigations, defaults, unpaid invoices and threatened proceedings.
- Employment, intellectual-property, asset, data and compliance records within the agreed scope.
- Management contacts who can answer focused factual questions.
A template, draft or data-room label is not proof of the agreement in force. Executed copies and later variations are essential. Missing records should be recorded as a limitation and, where material, elevated as a finding.
How legal due diligence is performed
- Define the decision. Understand what is being acquired, invested in or financed and what must be true for the client to proceed.
- Agree scope and materiality. Set entity, period, document categories, thresholds, priorities, exclusions and reporting format.
- Build the document map. Index the data room, identify gaps and separate executed records from drafts.
- Review priority evidence. Test contracts, corporate records, licences and disputes against the transaction assumptions.
- Raise focused questions. Request missing documents and factual explanations without treating unverified answers as evidence.
- Report by risk and action. Link each material finding to its source, impact, owner and proposed next step.
- Update before closing. Record new documents, consents, negotiated protections and unresolved residual risks.
Materiality and risk grading
Reviewing every document at the same depth can consume time without improving the decision. Materiality may be based on value, duration, revenue concentration, operational dependence, exclusivity, regulatory significance, liability, termination rights or the likelihood that third-party consent is required. Exceptions should remain possible for a lower-value contract that controls a key asset, licence, customer or technology.
| Priority | Meaning | Reporting approach |
|---|---|---|
| Critical | Potentially affects signing, closing, legality or the core transaction assumption. | Escalate immediately with evidence, uncertainty and available options. |
| Material | May affect price, protection, consent, timetable or post-closing action. | Include in the main findings and transaction documents. |
| Operational | Requires remediation, monitoring or integration planning. | Assign an owner and target date. |
| Information gap | Evidence is missing, incomplete or inconsistent. | Request the record and state what cannot yet be concluded. |
Official verification in Kuwait
Depending on the transaction, public and official checks may include the Kuwait Ministry of Commerce and Industry, its commercial registry services, the Kuwait Business Center, the KDIPA Investors Service Center and the Kuwait Ministry of Justice. The relevant authority depends on the entity, activity and transaction. A public portal check does not replace certified records, management evidence or advice on the specific deal.
What a useful due diligence report should deliver
The report should be concise enough for decision-makers and traceable enough for counsel and the transaction team. Each material finding should identify the document, clause or evidence; explain the issue and uncertainty; state the possible deal impact; and propose a practical action. Outputs may include a red-flag report, detailed schedule, consent tracker, closing checklist, risk matrix and list of post-closing actions.The report must also state its limitations: documents not supplied, translations not verified, factual answers not evidenced, searches not available, specialist matters excluded and changes received after the cut-off date. Clear limitations protect the quality of the decision; they are not a substitute for completing the missing work.
Cross-border and overseas transaction teams
Clients outside Kuwait can begin with a written transaction summary, group chart, target details, data-room index and timetable. A Kuwait review can then be coordinated with foreign counsel and financial or technical advisers while keeping the Kuwait scope distinct. Identity, authority, conflict and engagement checks are required before substantive work begins.
Frequently asked questions
How early should due diligence begin?
Begin once the proposed transaction, target and initial document set are sufficiently defined. Early review leaves time to address consent, licence, ownership and termination issues before the closing timetable becomes fixed.
Can the review cover only material contracts?
Yes. The scope may use financial and operational thresholds, while allowing exceptions for agreements whose risk is disproportionate to their value.
What if the data room is incomplete?
Missing information should be logged, requested and reflected in the report. No positive conclusion should be inferred merely because a document was not provided.
Does due diligence confirm that the target has no liabilities?
No. It reports findings within an agreed scope and based on the evidence available. Hidden, inaccurate or withheld information may not be discoverable.
Can the findings be used in the transaction agreement?
Yes. Material issues may inform conditions, disclosures, warranties, indemnities, covenants, price mechanisms or post-closing actions, subject to negotiation and transaction-specific advice.
How long does a review take?
Timing depends on the scope, number and quality of documents, languages, response time, transaction complexity and reporting deadline. A data-room index and materiality proposal help estimate the work.
Can overseas investors commission Kuwait due diligence remotely?
Yes. The initial process can be managed through written instructions and electronic documents. Additional originals, certified records or local verification may be required depending on the transaction.
Does the report decide whether the client should proceed?
The report supports that decision by presenting legal findings, limitations and options. The final commercial decision belongs to the client and its transaction team.
Request a written due diligence appointment
To request an appointment with Lawyer Khaled Mufrej Al-Dalmani, send a written WhatsApp message with your name, company or role, whether you are contacting from Kuwait or abroad, the transaction type, target, approximate document volume and deadline. Your message helps the office identify the matter and arrange the appropriate review.Privacy notice: Please do not send highly confidential, privileged, identity or transaction documents until the office confirms the appropriate secure method and completion of the necessary preliminary checks.Last reviewed: August 2026. This page provides general information and is not a legal opinion on any transaction.
Related Kuwait Legal Guides
- Foreign investment and market-entry legal support in Kuwait
- Corporate governance and legal compliance in Kuwait
For the scope of representation and ongoing support, see English-speaking legal services in Kuwait.
Lawyer Khaled Mufrej Al-Dalmani — المحامي خالد مفرج الدلماني, Kuwait. Written enquiries and appointments: WhatsApp +965 66669028.



